 Exeter Auto Loan
A repair quote that feels high is not always wrong, but some quotes are padded, vague or built on unnecessary work. Exeter Auto Loan connects drivers with lenders for repair costs, and the smartest borrowing starts with a fair estimate, because every extra $300 on the invoice becomes $300 plus interest on a personal loan. This guide covers the warning signs of an inflated quote, typical US price ranges for common jobs, the questions that expose padding and how to get a fair second opinion.
How can you tell if a car repair quote is too high?
A quote is likely too high when its labor hours exceed published book time, parts are marked up far beyond retail, the total sits well above two other local estimates, or the line items are vague.
Shops set prices from three ingredients: the labor rate, the number of labor hours and the parts cost. Labor rates at independent shops commonly run about $100 to $160 an hour, and dealerships often charge $150 to $220 or more. Labor hours should come from a standard labor guide, often called book time, which lists how long a trained technician typically needs for each job on your specific vehicle. Parts are usually marked up from the shop's cost; a markup of 30% to 100% on small parts is common, but triple retail is a warning sign.
When a quote feels off, break it into those three pieces. If one piece is far out of line, you have found the problem. If all three look normal and the total is still painful, the quote may be fair and the job is simply expensive.
What do common car repairs typically cost?
Many routine repairs fall into fairly predictable ranges at independent shops, from about $150 for a battery to $3,500 or more for a transmission, so comparing your quote to these ranges is a fast first check.
| Repair (typical sedan) | Typical independent shop range (estimate) | Typical book time |
|---|---|---|
| Front brake pads and rotors | $300 to $600 | 1.5 to 2.5 hours |
| Battery replacement | $150 to $300 | 0.3 to 0.8 hours |
| Alternator | $450 to $800 | 1.0 to 3.0 hours |
| Starter motor | $350 to $700 | 1.0 to 2.5 hours |
| Water pump | $400 to $900 | 2.0 to 5.0 hours |
| Timing belt kit with water pump | $700 to $1,300 | 3.5 to 6.0 hours |
| Front struts (pair) with alignment | $700 to $1,300 | 2.5 to 4.0 hours |
| Catalytic converter | $1,000 to $2,500 | 1.0 to 3.0 hours |
| Rebuilt transmission | $2,500 to $4,500 | 8.0 to 14.0 hours |
These are broad estimates. Trucks, European models, hybrids and all-wheel-drive vehicles often run higher, and big-city labor rates add to every line. Use the table as a sanity check, not a price list. The cluster guide on auto repair loans also lists cost ranges by repair type if you are planning how to pay.
What are the warning signs of a padded repair estimate?
Watch for vague line items, labor charged twice for overlapping work, a long list of "recommended" extras with no inspection notes, inflated shop-supply fees, and pressure to approve everything today.
- Vague descriptions. "Front-end work, $1,150" tells you nothing. A fair estimate names each part and its labor.
- Overlapping labor. When a timing belt and water pump are replaced together, much of the disassembly is shared. A quote that charges full book time for both separately is double-billing.
- Stacks of flushes. Power steering, transmission, coolant, brake fluid and fuel injection flushes all at once on a car that has no related symptom is a common upsell.
- High shop-supply fees. A small percentage for rags and cleaners is normal, often capped around $30 to $50. A flat 15% of the bill is not.
- Diagnostic fees that are not credited. Many shops apply the diagnostic charge to the repair if you approve it. Ask.
- Pressure tactics. "This price is only good today" or "the car is unsafe to drive off the lot" without a written explanation.
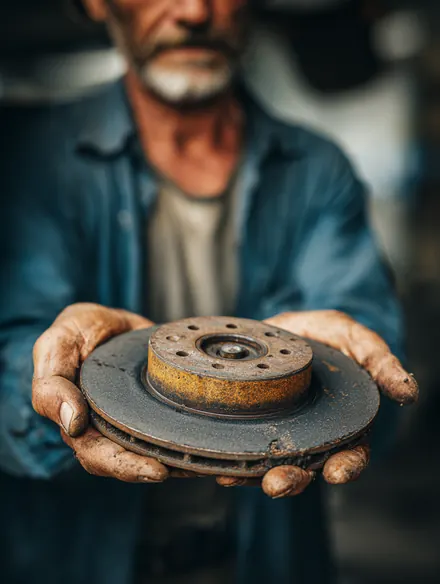
- No old parts offered. A shop confident in its diagnosis should be happy to show you the worn component.
One sign alone does not prove bad faith. Two or three together suggest it is time for a second opinion.
What questions should you ask the mechanic about a quote?
Ask which labor guide and hourly rate they used, whether parts are OEM, aftermarket or remanufactured, which items are urgent versus optional, and whether you can see the worn parts before and after the repair.
Polite, specific questions usually get honest answers, and they signal that you are paying attention. Try these at the counter:
- "What is your hourly labor rate, and how many hours are you billing for each item?"
- "Are these original-equipment parts, quality aftermarket parts or remanufactured? What is the price difference?"
- "Which of these items is a safety issue now, which can wait three months, and which is preventive?"
- "What did the inspection actually measure? For example, how many millimeters are left on the brake pads?"
- "Is there a warranty on parts and labor, and for how many miles or months?"
- "Can you put the estimate in writing and hold it for 48 hours while I compare?"
Measurements are especially telling. Brake pads are usually replaced around 3 millimeters. If the shop says your pads are at 7 millimeters but still recommends replacement, ask why.
How do you get a fair second opinion on a repair?
Take the written estimate, including the diagnostic notes and trouble codes, to one or two other shops and ask them to quote the same job on the same parts, rather than starting a fresh diagnosis from scratch.
A second diagnosis can cost $100 to $180, so give the second shop the first shop's findings and ask for a price to perform that exact work. If they disagree with the diagnosis itself, that is valuable information too. Choose shops with ASE-certified technicians, clear online reviews that mention honesty and pricing, and a written warranty of at least 12 months or 12,000 miles.
A real example of how much this can matter: a fictional retiree in Cincinnati was quoted $1,840 for "front suspension repair" on a ten-year-old sedan. The second shop found only one worn sway bar link and a leaking strut, quoted $690 including an alignment, and showed her the play in the link with the car on the lift. The first quote was not necessarily dishonest; it bundled preventive work. But knowing the difference saved her about $1,150.
Is a dealership quote always higher than an independent shop?
Dealership quotes are often 20% to 40% higher for the same job because of higher labor rates and factory parts, but dealers can be the better choice for warranty, recall and complex electronic repairs.
Take a front brake job quoted at $780 by a dealer and $520 by an independent shop. Part of the gap is labor rate, and part is the factory pad and rotor price. For a common wear item on a car out of warranty, the independent quote is usually the better value. For an airbag module, a software update, or anything covered by a recall or extended warranty, the dealer may be the only sensible choice and may cost you nothing.
Also check whether your car has an open recall or a technical service bulletin for the problem. A manufacturer sometimes extends coverage on a known defect, which can turn a $1,600 bill into a $0 one.
Can you negotiate a car repair quote?
Yes, within reason: you can ask for aftermarket parts, drop optional items, request that overlapping labor be removed, or ask the shop to match a written competing quote, though rates themselves are rarely negotiable.
- Swap parts tiers. A quality aftermarket alternator might cost $220 instead of a $420 factory part.
- Phase the work. Approve the safety item today and schedule the preventive items for next month.
- Ask about overlap. "Since the belt is already off for the water pump, can the labor on the tensioner be reduced?"
- Bring a written quote. Many shops will match or come close rather than lose the job.
- Ask about cash or debit discounts. Some small shops offer 3% to 5% off to avoid card processing fees.
Avoid supplying your own parts unless the shop agrees in advance. Many will not warranty labor on customer-supplied parts, which can cost more in the long run.
What are the options for paying a verified repair quote?
Once the quote checks out, drivers typically choose between savings, a shop payment plan, a credit card or a fixed-rate personal loan, and the right pick depends on the amount, the timeline and the total cost of each.
| Payment option | Works best when | Watch out for |
|---|---|---|
| Emergency savings | You have the cash and can rebuild it within a few months | Draining the fund completely before the next surprise |
| Shop payment plan | The shop offers a short, low-cost plan in writing | Deferred interest if the promo balance is not cleared on time |
| Credit card | The bill is small and you can repay within one or two statements | High ongoing interest with minimum payments |
| Personal loan | The repair is necessary, larger, and you want a fixed payment and end date | Higher APRs for fair or poor credit; origination fees |
Personal loans are a common choice for repairs between about $800 and $4,000, where a card balance would take too long to clear and savings fall short. A personal loan gives you a fixed payment and a known payoff date, which makes it easier to plan around. The downside is cost: personal loans for drivers with fair or poor credit often carry APRs in the upper half of the roughly 6% to 35.99% range.
That is exactly why the quote matters. Personal loans charge interest on every dollar borrowed, including any padded labor or unneeded flushes. Before comparing personal loan offers, finalize the repair list so the loan covers only the work you agreed to. If the shop later finds an additional problem, ask for a separate written estimate rather than a verbal add-on, and decide whether that item can wait.
Timing also matters. Many shops will hold a quote for a few days while you arrange payment, and some will start parts ordering once you confirm. Personal loan funding is often the next business day after approval, sometimes the same day, but it is never promised, so tell the shop your expected timeline instead of approving the work before the money is in place.
How should a fair quote shape an Exeter Auto Loan request?
Request a loan only after you have a written, verified estimate, and borrow close to that figure, because a smaller Exeter Auto Loan request based on a fair quote costs less in interest and is often easier for lenders to place.
Exeter Auto Loan is a free service that matches drivers with lenders; it does not lend money itself. An Exeter loan request goes to a network of independent lenders offering personal loans of $500 to $5,000, and each lender decides whether to make an offer, at what APR and for what term. There is no fee to submit and no obligation to accept. Submitting usually triggers a soft credit check, and a lender may run a hard inquiry before final approval. Approval is never assured.
The quote directly shapes what a personal loan costs. As a representative example, $2,000 for 24 months at 24.99% APR is about $106.73 a month and about $2,561.59 in total (estimate). If a second opinion trims that repair to $1,400, the same term and APR would bring the payment to roughly $74.71 and save around $170 in interest (estimate). Check typical pricing on the rates page, and model payments with the car loan calculator before you send an Exeter car loan request.
When is a high repair quote actually fair?
A high quote is often fair when the repair involves an engine or transmission, rare or backordered parts, rust-seized components, hybrid or electric systems, or a shop that includes a long warranty and genuine parts.
Some vehicles simply cost more to fix. Replacing a water pump on a transverse V6 that requires removing the intake manifold can take five hours where a four-cylinder takes two. In states with heavy road salt, seized bolts add labor that a book estimate does not show, and an honest shop will warn you of that possibility up front. Hybrid battery and inverter work requires special training and equipment. A shop that offers a 36-month, 36,000-mile warranty on a transmission rebuild is pricing in risk that a 90-day warranty shop is not.
The goal is not the lowest number on paper. It is a quote you understand, for work you actually need, from a shop that stands behind it. If you reach that point and the price is still more than you can pay from savings, you are making an informed decision about whether a personal loan, savings or a payment plan is the right way to finance a necessary repair, rather than a rushed one.
Frequently Asked Questions
Can a shop charge more than the written estimate?
Many states require shops to get your authorization before exceeding a written estimate by more than a set amount or percentage. Rules vary by state, so ask the shop to call you before any additional work. Keep a copy of the signed estimate.
Is a free inspection a red flag?
Not by itself, since many shops use free inspections to attract customers. The risk is a long list of recommended work that follows. Ask for measurements and photos for each item before approving anything.
How do I check book time for my repair?
Ask the shop to show the labor guide entry for your vehicle and job. Some consumer repair-estimate websites also list typical labor hours by make, model and year. Compare the billed hours with that figure.
Related posts
Most car repairs cost $250 to $1,200, but transmissions and engine work can top $5,000. See typical US price ranges by job, what drives quotes up, and how to plan.

Bad credit and a $2,000 car bill? Learn what lenders check, what a high-APR offer really costs, which products to avoid and how to improve your odds.
